BMO Upgrades Enbridge to Outperform with CDN$79.50 Target as CEO Succession and Tallgrass Deal Weigh on Stock
BMO upgraded Enbridge to Outperform Tuesday with CDN$79.50 target; National Bank holds CDN$81. The stock yields 5.78% after a 15% slide from July's peak.
BMO Capital Markets upgraded Enbridge Inc. to Outperform from Market Perform on Tuesday, raising its price target to CDN$79.50 from CDN$79.00. Shares traded near a 52-week low with a dividend yield of 5.78% after falling more than 15% since mid-July. BMO cited Enbridge's negligible commodity price exposure, diverse North American footprint, and improving visibility to its 5% annual growth target through end of decade.
Two Banks Independently Converge on 28 Percent Total Return
National Bank Financial analyst Patrick Kenny upgraded Enbridge to Strong-Buy on September 10, setting a CDN$81 price objective after coming off research restriction following the company's equity offering. Kenny noted that shares had dropped more than 15% since mid-July, compressing the 2027 EV/EBITDA multiple to under 12.5x against a long-term average of 13.0x. The stock traded approximately 15% below his sum-of-the-parts valuation of CDN$77 per share at the time of his note. Kenny calculated a 12-month total return opportunity of 28%, including dividends.
BMO's CDN$79.50 target and National Bank's CDN$81 objective are independently derived but arrive at essentially the same conclusion. Enbridge's 5.78% dividend yield, combined with price appreciation toward either target, produces a total return close to Kenny's stated 28% figure. Enbridge has raised its dividend for 23 consecutive years, most recently declaring a 3% increase with its 2026 financial guidance. Both banks argue the current EV/EBITDA premium to peers, at 12.5x versus an average of 11x, is justified by the company's growth visibility and fee-based revenue certainty.
What Triggered the Selloff: Two Announcements in 48 Hours
The 15% decline from mid-July traced directly to two back-to-back announcements in early September. On September 8, Enbridge disclosed that President and Chief Executive Officer Greg Ebel would retire effective December 31, 2026, with Michele Harradence appointed as his successor. The following day, Enbridge announced a US$2.55 billion acquisition of Tallgrass Energy's crude oil transportation business and a US$600 million tuck-in of Salt Creek Midstream's Delaware Basin gathering assets. Simultaneously, the company launched a CDN$3.0 billion equity offering to partially fund both transactions.
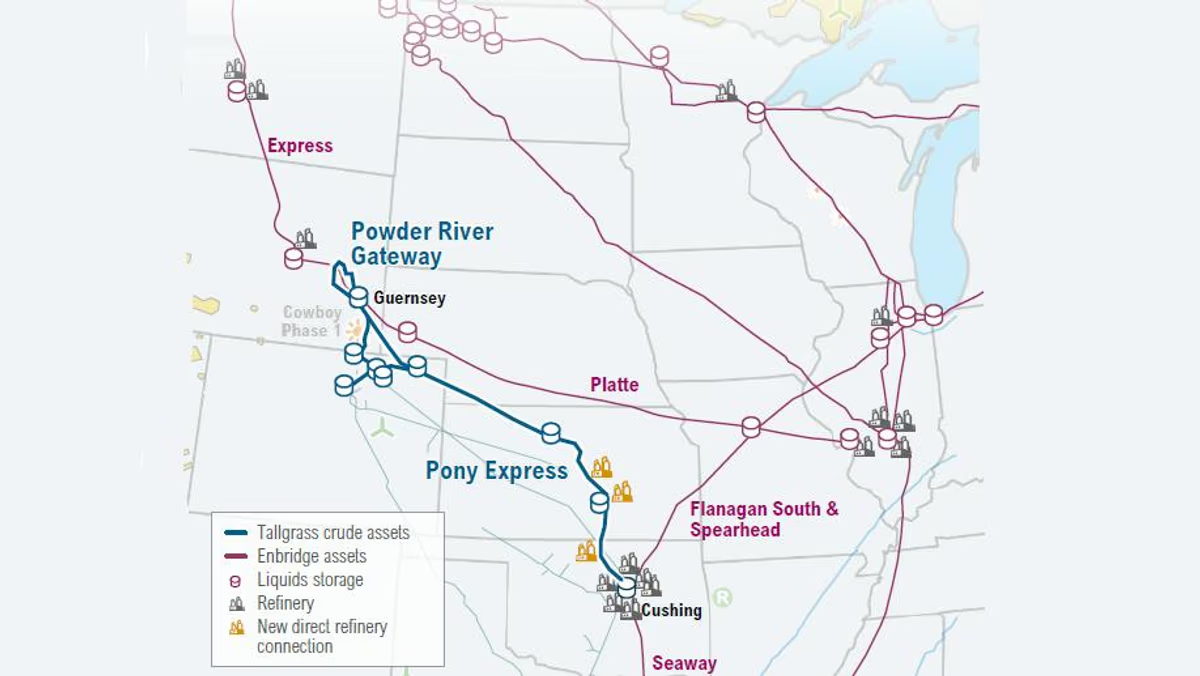
Oil Authority covered the Tallgrass transaction in detail at announcement, including the Pony Express capacity addition and the Williston Basin rig surge that underpins volume demand: Enbridge Pays $2.55B for Tallgrass Crude Business Including Pony Express Pipeline, Adding 460,000 bpd Rockies Corridor as Williston Rigs Surge to 16-Month High. The stock fell as investors priced in near-term EPS dilution from the equity raise and uncertainty around the leadership change. Both BMO and National Bank came off mandatory research restriction after underwriting the offering. Each bank's note concludes the selloff has been excessive relative to the transaction's long-run strategic value.
Enbridge's Five Business Segments After the Tallgrass and Salt Creek Additions
Enbridge's Liquids Pipelines segment operates the Mainline System, widely considered the world's longest heavy crude pipeline network, transporting approximately 3 million barrels per day from Alberta's oil sands to US Midwest and Gulf Coast refineries. The Pony Express Pipeline, acquired through the Tallgrass transaction, adds a 460,000 bpd corridor connecting Rocky Mountain and Denver-Julesburg Basin producers to the Cushing, Oklahoma trading hub. Salt Creek Midstream adds crude oil gathering capacity in the Delaware Basin of the Permian, complementing Enbridge's existing US midstream footprint.
Enbridge's Gas Transmission segment spans approximately 31,178 kilometres of natural gas pipelines across 31 US states and four Canadian provinces, including Algonquin Gas Transmission and Texas Eastern. The DCP Midstream joint venture with Phillips 66 extends that reach further into gathering and processing. Gas Distribution and Storage, through Enbridge Gas Inc., serves approximately 3.8 million residential and commercial customers in Ontario, making it Canada's largest natural gas utility. Renewable Power generation rounds out the portfolio with wind, solar, and waste heat recovery assets.
The scale of this infrastructure is central to BMO's upgrade rationale. All five segments generate regulated or contracted fee revenue with no direct exposure to commodity prices. Elevated crude prices support throughput volumes across the Mainline and Pony Express as Alberta and Rocky Mountain producers increase drilling activity, but Enbridge collects the same regulated tariff per barrel whether WTI trades at $70 or $103.
Crude Prices Stay Elevated as Saudi East-West Pipeline Remains Offline
ICE Brent front-month crude was priced at $108.50 per barrel on Tuesday, a gain of 1.9% on the day and 6.3% on the week, per ICE Futures Europe live settlement data. CME WTI front-month traded at $103.57 per barrel on Tuesday's NYMEX session, up $2.18 on the day, per Investrade market data. Saudi Arabia's East-West pipeline remained offline following drone strikes on pumping stations, keeping an alternative to Hormuz Strait transit capacity unavailable, according to Reuters.
The EIA September 2026 Short-Term Energy Outlook projects Middle East crude flows will remain constrained through the fourth quarter, with shut-in production averaging 5.7 million barrels per day in Q4 2026. Global oil production fell 1.6 million barrels per day month-over-month to 100.1 million barrels per day in August, per the IEA September 2026 Oil Market Report. For Canadian producers shipping oil sands volumes on the Enbridge Mainline, WTI above $103 per barrel in US-dollar terms translates to strong Canadian-dollar realized prices, supporting throughput demand. Enbridge itself earns regulated tariffs and does not benefit directly from the commodity price level.
Published by Oil Authority, edited by Adam Humphreys
Submit a Correction
Spotted a factual error? Free account required to submit a correction.