Goldman Sachs Raises Year-End Brent Target to $85 as Bank of America and HSBC Also Upgrade; ICE Friday Settlement of $104.61 Sits $14 to $21 Above Consensus
Goldman Sachs, BofA and HSBC raised Brent year-end forecasts Sunday, but all three targets trail Friday's $104.61 ICE settlement by up to $21 per barrel.
Three major investment banks raised their 2026 year-end Brent crude forecasts on Sunday, September 13, yet every revised target sits below Friday's ICE settlement. Goldman Sachs lifted its December 2026 Brent target by $5 per barrel to $85. Bank of America raised its second-half 2026 Brent forecast to $83 per barrel. HSBC set a 2026 full-year Brent average of $90 per barrel. ICE Brent's November 2026 contract closed at $104.61 per barrel on Friday, leaving a gap of $14 to $21 per barrel between analyst consensus and the actual market.
The Revised Forecasts and Where They Land
Goldman Sachs commodity analysts cited lower-than-expected OECD inventory builds as the driver behind Sunday's $5 upgrade. The bank's December 2026 Brent target of $85 per barrel and WTI target of $80 per barrel reflect a base case where Hormuz shipping disruptions ease before year-end. Bank of America landed at $83 per barrel for the second half, the most bearish of the three banks. HSBC's $90 full-year average aligns with the EIA's September 9 Short-Term Energy Outlook, which projects Brent at $90 per barrel for the second half of 2026.
The EIA noted that global oil prices averaged $91 per barrel in August 2026, $7 per barrel above July's level. Goldman and Bank of America both sit below that August realized average. The three-bank range of $83 to $90 per barrel represents a $7 spread at this stage of the year. Forecaster disagreement is itself a signal: the range reflects genuine uncertainty about how long disrupted Gulf flows persist.
Goldman's 54% Year-Over-Year Revision
Goldman Sachs entered 2026 projecting Brent would average $56 per barrel for the year, with risk of falling to the low $50s by late 2026 due to a forecast 2.3 million barrel-per-day global surplus. Eight months later, with Brent at $104.61 per barrel on Friday's close, the bank has raised its year-end target more than 50% above that original projection. Even so, the current spot price sits $19.61 per barrel above Goldman's revised $85 target. Sunday's upgrade narrows the gap only marginally; the spot premium has grown faster than the forecast.
Goldman also disclosed a tail-risk scenario: if Gulf production and export disruptions remain significant through Q4, Brent could breach $120 per barrel. Bank of America did not publish an equivalent upside scenario in its upgrade. The gap in risk framing between the two banks is meaningful: Goldman models a wider distribution of Q4 outcomes than its peer. Investors hedging year-end exposure must choose between two quite different probability distributions.
Calculating the Implied Hormuz Risk Premium
Averaging the four published forecasts (Goldman's $85, Bank of America's $83, HSBC's $90 and the EIA's $90) yields a consensus year-end Brent target of $87.00 per barrel. Friday's ICE settlement of $104.61 per barrel sits $17.61 above that consensus. That difference represents the market's implied Hormuz risk premium: the gap between what crude fetches under current disruption and what analysts believe it would fetch if normal Persian Gulf flows resumed.
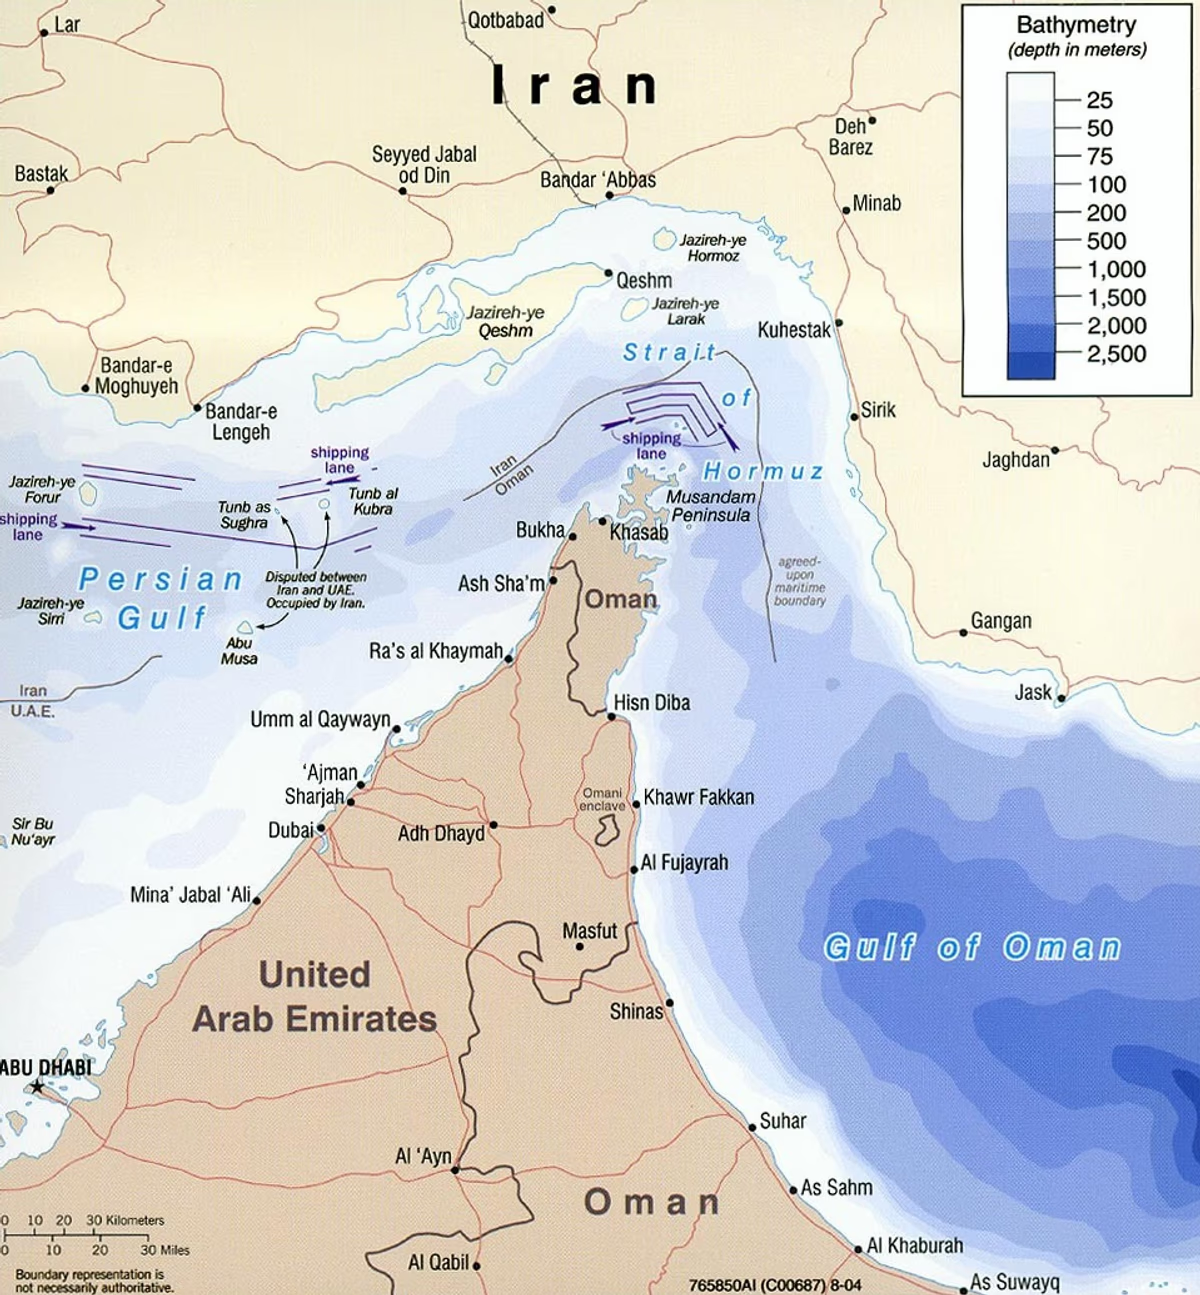
Roughly 17 million barrels of crude and petroleum products per day moved through the Strait of Hormuz in pre-disruption conditions, per EIA estimates. At $17.61 per barrel above the analyst baseline, those volumes carry an excess cost of $299 million per day. Over a full quarter at that rate, excess energy costs reach $27.2 billion above the no-disruption baseline, borne by refiners, importers and ultimately consumers.
When Goldman's year-end Brent target stood at $80 per barrel, Brent was trading in the low $90s, as tracked in an earlier Oil Authority analysis of Goldman's Q4 $80 target and WCS Alberta netbacks. Sunday's $5 upgrade to $85 barely kept pace with Brent's rise from the low $90s to $104.61. The analyst-to-spot gap has widened, not closed, since that prior target was set.
OPEC+ Completes the Voluntary Cut Rollback
A potential counterweight to Hormuz-driven tightness is OPEC+'s September production increase. Seven OPEC+ nations, including Saudi Arabia, agreed on August 2 to raise collective output by 188,000 barrels per day in September. Saudi Aramco, the state-owned producer executing Saudi Arabia's quota, will manage the incremental output from Arabian Peninsula fields. The move completed the phased rollback of 1.65 million barrels per day in voluntary cuts first enacted in 2023, the sixth consecutive monthly increase.
Friday's Brent settlement of $104.61 shows six months of output increases have not offset the Hormuz-driven bid for spot cargoes. OPEC+ retains 2 million barrels per day in deeper cuts dating to 2022, which remain in place through year-end. Whether the group pauses after completing the voluntary rollback or extends production growth into Q4 will shape the analyst-to-spot gap. A pause supports Goldman's $120 upside scenario; a further increase would add downward pressure on the $17.61 risk premium.
Western Canadian Producers Capture the Upside
Alberta heavy oil producers are collecting substantially higher realized prices than a year ago. The Alberta Energy Regulator projects the WCS-WTI differential at $12.00 per barrel for 2026. With WTI settling at $100.05 per barrel on Friday's CME close, Western Canadian Select crude fetched $88.05 per barrel. Brent's 59.5% year-over-year advance per Trading Economics data places WCS in the mid-$50s a year ago, a gain of more than $30 per barrel.
Suncor Energy, Canada's largest integrated oil company, produces bitumen and synthetic crude priced against WCS benchmarks. Imperial Oil, which ExxonMobil controls with an 82.7% stake, operates the Kearl and Cold Lake oil sands and captures the same WCS upside. The $32 per barrel improvement in WCS pricing over 12 months, applied across Alberta's estimated 1.5 million barrels per day of heavy crude, represents $17.5 billion in annualized incremental revenue before royalties. Those gains flow to operators and provincial governments as US dollar revenues, widening Alberta's fiscal windfall from elevated oil prices.
Published by Oil Authority, edited by Adam Humphreys
Submit a Correction
Spotted a factual error? Free account required to submit a correction.