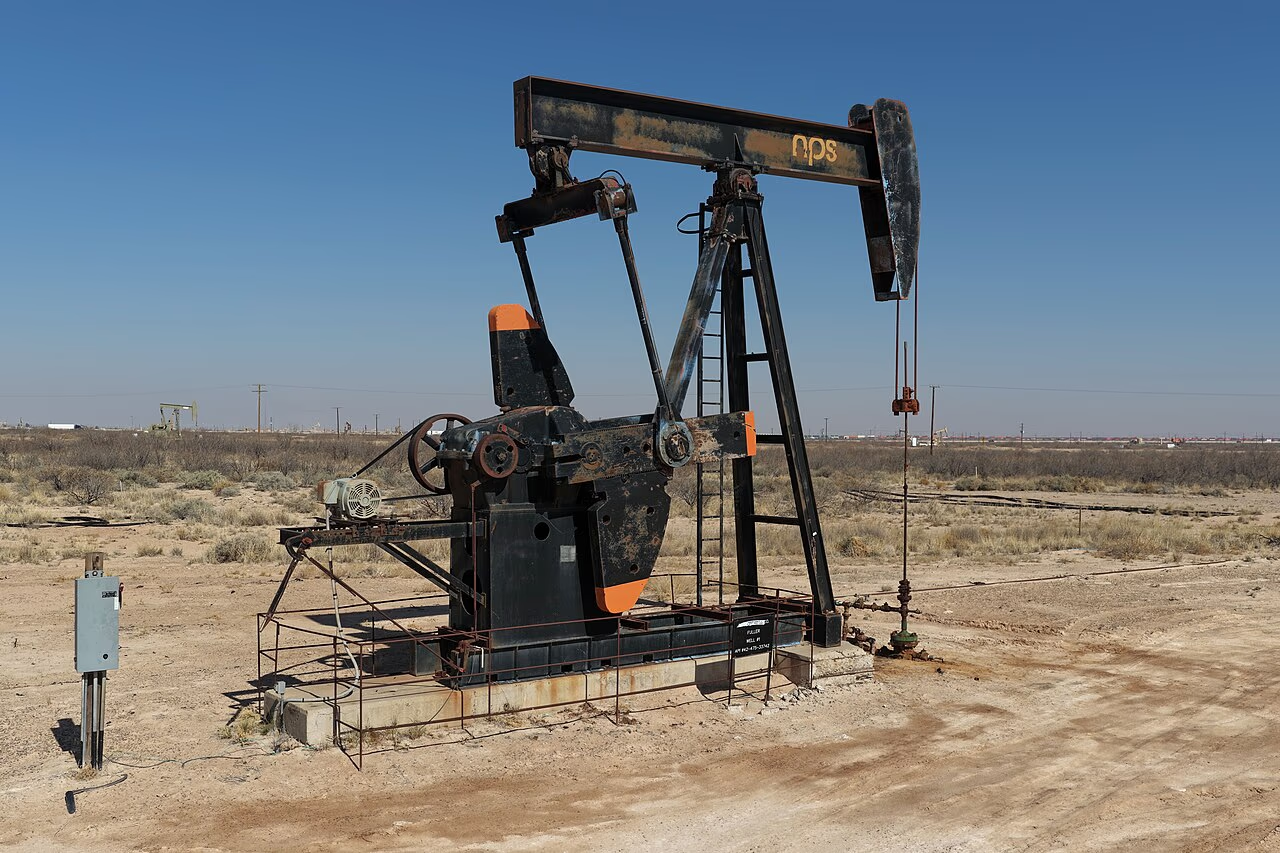
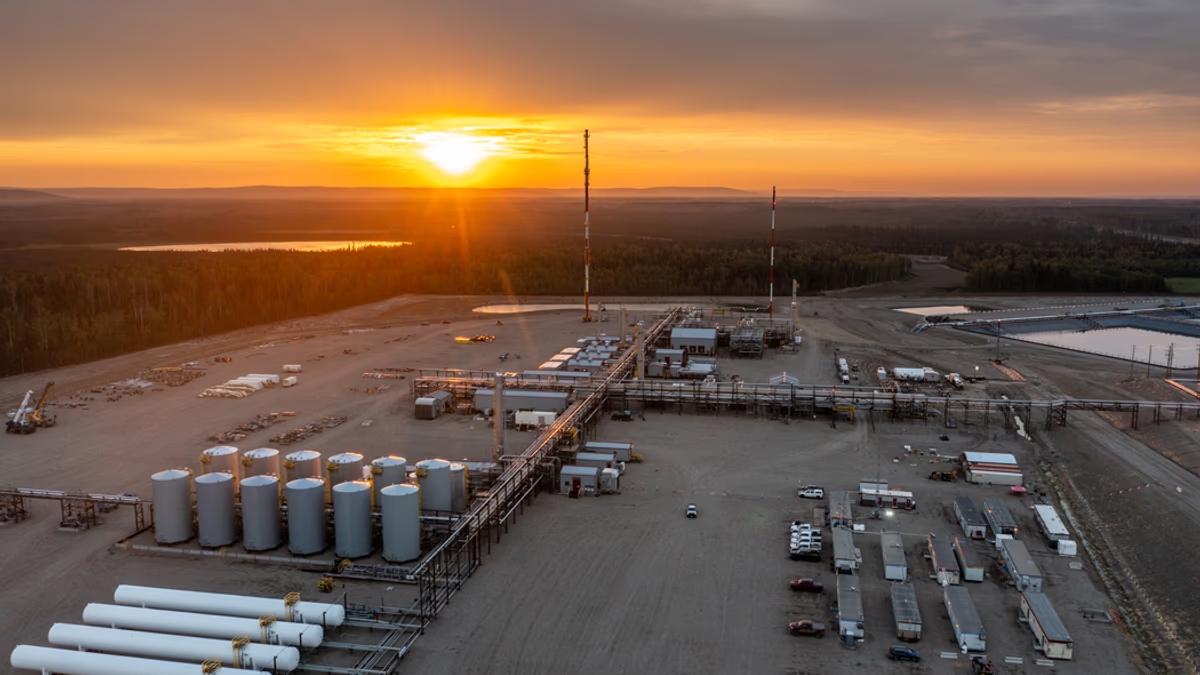
Tamarack Valley and Headwater Exploration Agree C$10 Billion Merger to Create Canada's Largest Clearwater Oil Producer
Tamarack Valley and Headwater merge for C$10B to form Canada's top Clearwater oil producer, targeting 80,000 boe/d at a $37/bbl free-cash-flow breakeven.
Canadian oil producers Tamarack Valley Energy and Headwater Exploration announced on September 8 a definitive agreement to merge in an all-stock transaction valued at C$10 billion (US$7.25 billion). The combined company will become Canada's largest publicly traded pure-play producer focused on Alberta's Clearwater Formation. The deal is expected to close in mid-fourth-quarter 2026, subject to shareholder, court, Competition Act, and TSX approvals.
Deal Structure and Advisors
Headwater shareholders will receive one Tamarack common share for each Headwater share held. Tamarack will issue 237.8 million new shares, leaving existing Tamarack shareholders with 66.5% of the combined entity and Headwater shareholders with 33.5%. RBC Capital Markets served as strategic advisor to Tamarack; BMO Capital Markets advised Headwater's independent committee. Both Tamarack and Headwater shares rose on announcement day, with Tamarack gaining more than 4% and Headwater gaining nearly 2%.
The merged company will carry more than 80,000 barrels of oil equivalent per day of run-rate production, more than 300 million barrels of proved and probable reserves, and more than 3,000 identified drilling locations. Core land covers over 1,500 sections in the Clearwater fairway, with principal positions at Marten Hills, Nipisi, and Marten Hills West in central Alberta. The combined company will pursue annual synergies of more than C$50 million, beginning consolidation of operations in 2027.
The Clearwater Premium: What Buyers Are Paying
At US$7.25 billion for 80,000 boe/d of run-rate production, the transaction implies a per-flowing-barrel acquisition cost of US$90,625. By contrast, Shell's acquisition of ARC Resources, which closed September 2, 2026, valued ARC at US$44,324 per flowing barrel (US$16.4 billion for 370,000 boe/d). The gap reflects commodity mix: Tamarack-Headwater produces oil, while ARC was primarily a Montney natural gas and liquids operation. At WTI's CME settlement of US$91.11 per barrel on Friday, October 2, Clearwater oil commands a higher enterprise value per unit of flow than Montney gas.
On a reserves basis, the deal values the combined 300-million-boe proved-and-probable base at US$24.17 per barrel. Shell's ARC acquisition implied US$8.20 per barrel on ARC's 2-billion-barrel Montney gas reserve base. The divergence underlines a market reality: with Brent ICE holding above US$102 per barrel at Friday's close and AECO gas trading far below that on an energy-equivalent basis, oil reserves carry a structural premium in current deal pricing.
Tributary Exploration: The Spinoff Most Coverage Missed
The merger carves out a new public company called Tributary Exploration Inc. Headwater's non-core assets, including Mannville-stack exploration rights, Handel thermal heavy oil opportunities, and McCully natural gas production in New Brunswick, transfer to Tributary rather than into the combined oil company. Headwater's Jason Jaskela will lead Tributary as a separate entity. This structure keeps the merged Tamarack-Headwater focused exclusively on Clearwater development, avoiding the operational dilution that comes with managing unrelated plays.
Clearwater's Rise and the Alberta Drilling Wave
The Clearwater Formation grew from 30,000 barrels per day in 2017 to 230,000 barrels per day by end-2025, according to World Oil data. Alberta issued 1,764 drilling licenses in the first half of 2026, the highest volume for that period since 2014, with nearly one in five permits targeting Clearwater plays, per World Oil reporting from July 2026. The formation's attraction is its cold-flow production model: Clearwater crude flows without steam injection, keeping per-barrel development costs well below those of oil sands bitumen.
As Oil Authority reported, Alberta's oil capex hit a record C$32.4 billion in 2025, with the AER projecting record provincial output. The Clearwater play's low-cost drilling economics have been a central driver of that capex cycle, drawing operators from large independents such as Canadian Natural Resources to smaller pure plays including Spur Petroleum and Obsidian Energy. Clearwater wells typically require no diluent, no steam infrastructure, and no tailings management, giving producers a capital-cycle advantage over oil sands peers.
Market Access and Current Pricing Context
The combined company has secured 25,000 barrels per day of Trans Mountain expansion capacity to Canada's West Coast, available in the first quarter of 2027, according to World Oil. Tamarack also holds 10,000 barrels per day of potential capacity on the proposed South Bow Prairie Connector. These commitments reduce the company's dependence on Midwest US refinery demand, which tightened sharply in September following simultaneous outages at ExxonMobil's 275,000-barrel-per-day Joliet refinery and reduced throughput at BP's 440,000-barrel-per-day Whiting facility.
Western Canadian Select traded at an average discount of US$18.78 per barrel versus WTI through October 2026 forward deliveries, wider than CIBC Capital Markets' full-year estimate of US$14.25 per barrel. As Oil Authority tracked earlier in September, Midwest refinery disruptions and Enbridge Line 5 flow constraints drove that widening. At WTI's CME Friday settlement of US$91.11 per barrel on October 2, a WCS-equivalent realized price of US$72.33 per barrel still clears the combined company's US$37 per barrel free funds flow breakeven by US$35.33 per barrel. At 80,000 boe/d, that margin generates more than US$1.03 billion of free cash flow annually at current strip prices.
Growth Plan and Leadership Transition
The merged company targets 10 to 12 percent annual Clearwater production growth, up from the 8 to 10 percent growth each company was pursuing independently. The quarterly dividend rises 20 percent to C$0.06 per share. Tamarack president Steve Buytels becomes president and CEO of the combined entity effective January 1, 2027, with incumbent Tamarack CEO Brian Schmidt transitioning to executive chairman on the same date.
The deal still requires shareholder votes at both companies, a court order, and clearance under Canada's Competition Act and Investment Canada Act. With the Competition Bureau and Investment Canada both involved, the mid-Q4 close timeline points to a November 2026 target. Neither company has disclosed a shareholder meeting date as of early October 2026.
Published by Oil Authority, edited by Adam Humphreys
Submit a Correction
Spotted a factual error? Free account required to submit a correction.