
Tourmaline Oil Lifts 2027 Free Cash Flow Estimate 71% to C$1.8 Billion
Quarterly cash flow of C$788.3 million and a C$3.41 per mcf realized gas price against AECO at C$1.59 support Tourmaline's 5% dividend increase.
Tourmaline Oil Corp. raised its 2027 free cash flow estimate by 71% to C$1.8 billion on Nov. 4, alongside third-quarter cash flow of C$788.3 million and a 5% dividend increase.
The estimate assumes AECO gas at C$2.19 per mcf and WTI at US$84.08 per barrel in 2027. For Canadian gas investors, the figure shows how much cash a large Calgary-based producer expects to keep when the domestic hub stays weak, because most of the upside comes from sales and hedges outside it.
Tourmaline's 2027 plan funds 4% to 6% growth from internal cash
The Calgary company set 2027 exploration and production spending at C$2.6 billion and expects production to average 655,000 barrels of oil equivalent per day, 4% to 6% above 2026. For 2028 it forecasts free cash flow of C$1.75 billion and output of 680,000 boe/d.
Tourmaline puts the free cash flow yield at about 7% in both years, based on a market capitalization near C$26 billion. Oil Authority's arithmetic agrees: C$1.8 billion divided by C$26 billion is 6.9%.
Third-quarter production averaged 593,730 boe/d. That was 6% below the 634,746 boe/d of a year earlier, according to the company's management discussion and analysis, and just under its 595,000 to 605,000 boe/d guidance. Tourmaline attributed part of the gap to storage injections, which trimmed sales volumes by about 4,564 boe/d.
Output has since recovered to 630,000 to 635,000 boe/d. The company forecasts a fourth-quarter average of 635,000 to 645,000 boe/d and a 2026 exit rate of at least 670,000 boe/d, a figure that includes storage withdrawals. About 80 wells are due on production this quarter, and the Groundbirch-Monias deep cut plant remains on schedule for a fourth-quarter 2027 start-up.
Gas sold above AECO earned C$1.82 per mcf more in the quarter
The AECO 5A benchmark averaged C$1.59 per mcf in the third quarter, up from C$0.64 a year earlier. Tourmaline's realized gas price was C$3.41 per mcf. By Oil Authority's calculation, that is a C$1.82 premium, or about 2.1 times the benchmark.
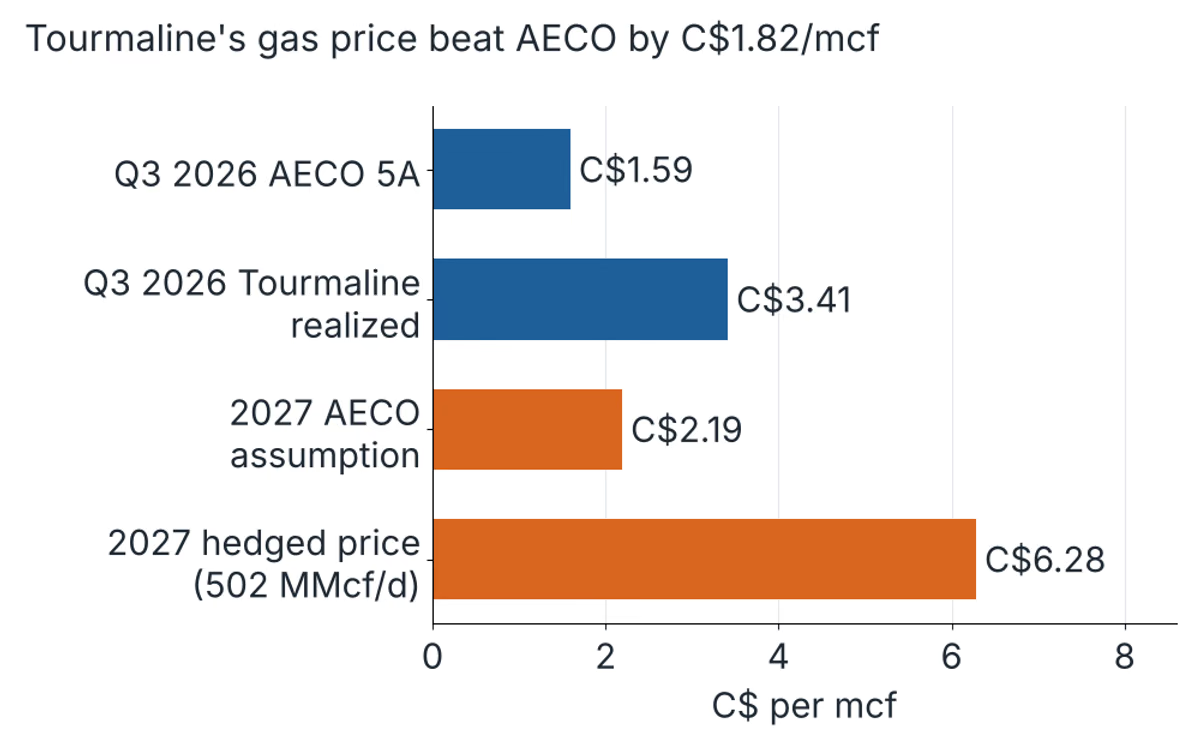
The premium comes from hedges and from contracts priced off overseas benchmarks. Tourmaline has 887 million cubic feet per day hedged for the rest of 2026 at C$5.07 per mcf, and 502 million cubic feet per day for 2027 at C$6.28 per mcf, nearly three times its own 2027 AECO assumption of C$2.19.
It also floats 105 million cubic feet per day against European TTF and Asian JKM prices through the end of 2026, rising to 137 million cubic feet per day in 2027. In the third quarter TTF averaged US$17.97 per million Btu and JKM US$21.08, against US$2.95 for NYMEX gas at its last trading day. The U.S. Energy Information Administration put Henry Hub spot at US$2.63 per million Btu on Nov. 3.
On Sept. 22 Tourmaline signed a seven-year agreement to deliver 30,000 million Btu per day to Centrica Energy from April 2031, priced off TTF less deductions. The company says the deal lifts its international exposure to 362,500 million Btu per day.
Net debt of C$1.54 billion sits below the C$1.75 billion target
Net debt stood at C$1.54 billion on Sept. 30, under the long-term target of C$1.75 billion and about 0.3 times forecast 2027 cash flow. Third-quarter capital spending of C$727.8 million left free cash flow of C$60.2 million, and net earnings were C$641.5 million, or C$1.64 per diluted share.
Tourmaline raised its quarterly base dividend 5% to C$0.525 per share, or C$2.10 a year, its 18th increase since 2018. It repurchased 1.3 million shares between Sept. 23 and Oct. 9 at an average of C$61.88.
The buyback is funded partly by the sale of Topaz Energy Corp. shares. On Oct. 8 Tourmaline closed the sale of 11.5 million Topaz shares at C$28.75 for gross proceeds of C$330.6 million, cutting its stake from 12.9% to 5.4%. Tourmaline said the sale "reflects the greater relative value Tourmaline currently sees in its own shares" and does not change its view of Topaz. Oil Authority's earlier report on Rubellite Energy's budget and its Topaz shares covers another holder of the royalty company.
From 2027 free cash flow, Tourmaline Oil plans to combine dividend increases, buybacks and possible special dividends. The next test of that policy is the raised dividend, payable Dec. 31 to shareholders of record on Dec. 15.
Published by Oil Authority, edited by Adam Humphreys
Submit a Correction
Spotted a factual error? Free account required to submit a correction.


