Brent Settles at $104.82 as Saudi Aramco Targets Partial East-West Pipeline Repair and $19 Risk Premium Holds
Brent settled at $104.82 on Thursday's ICE close as Saudi Aramco targets partial pipeline restoration; full repair could take weeks to months.
Brent crude settled at $104.82 per barrel on Thursday's ICE close, down $1.01 on the day. WTI crude settled at $101.91 per barrel on the CME, down $0.52. Thursday marked the third consecutive session of retreat since Brent's $109.44 intraday peak on September 12, when news of the Saudi East-West pipeline shutdown hit trading desks.
Saudi Aramco Targets Half Capacity Within Days
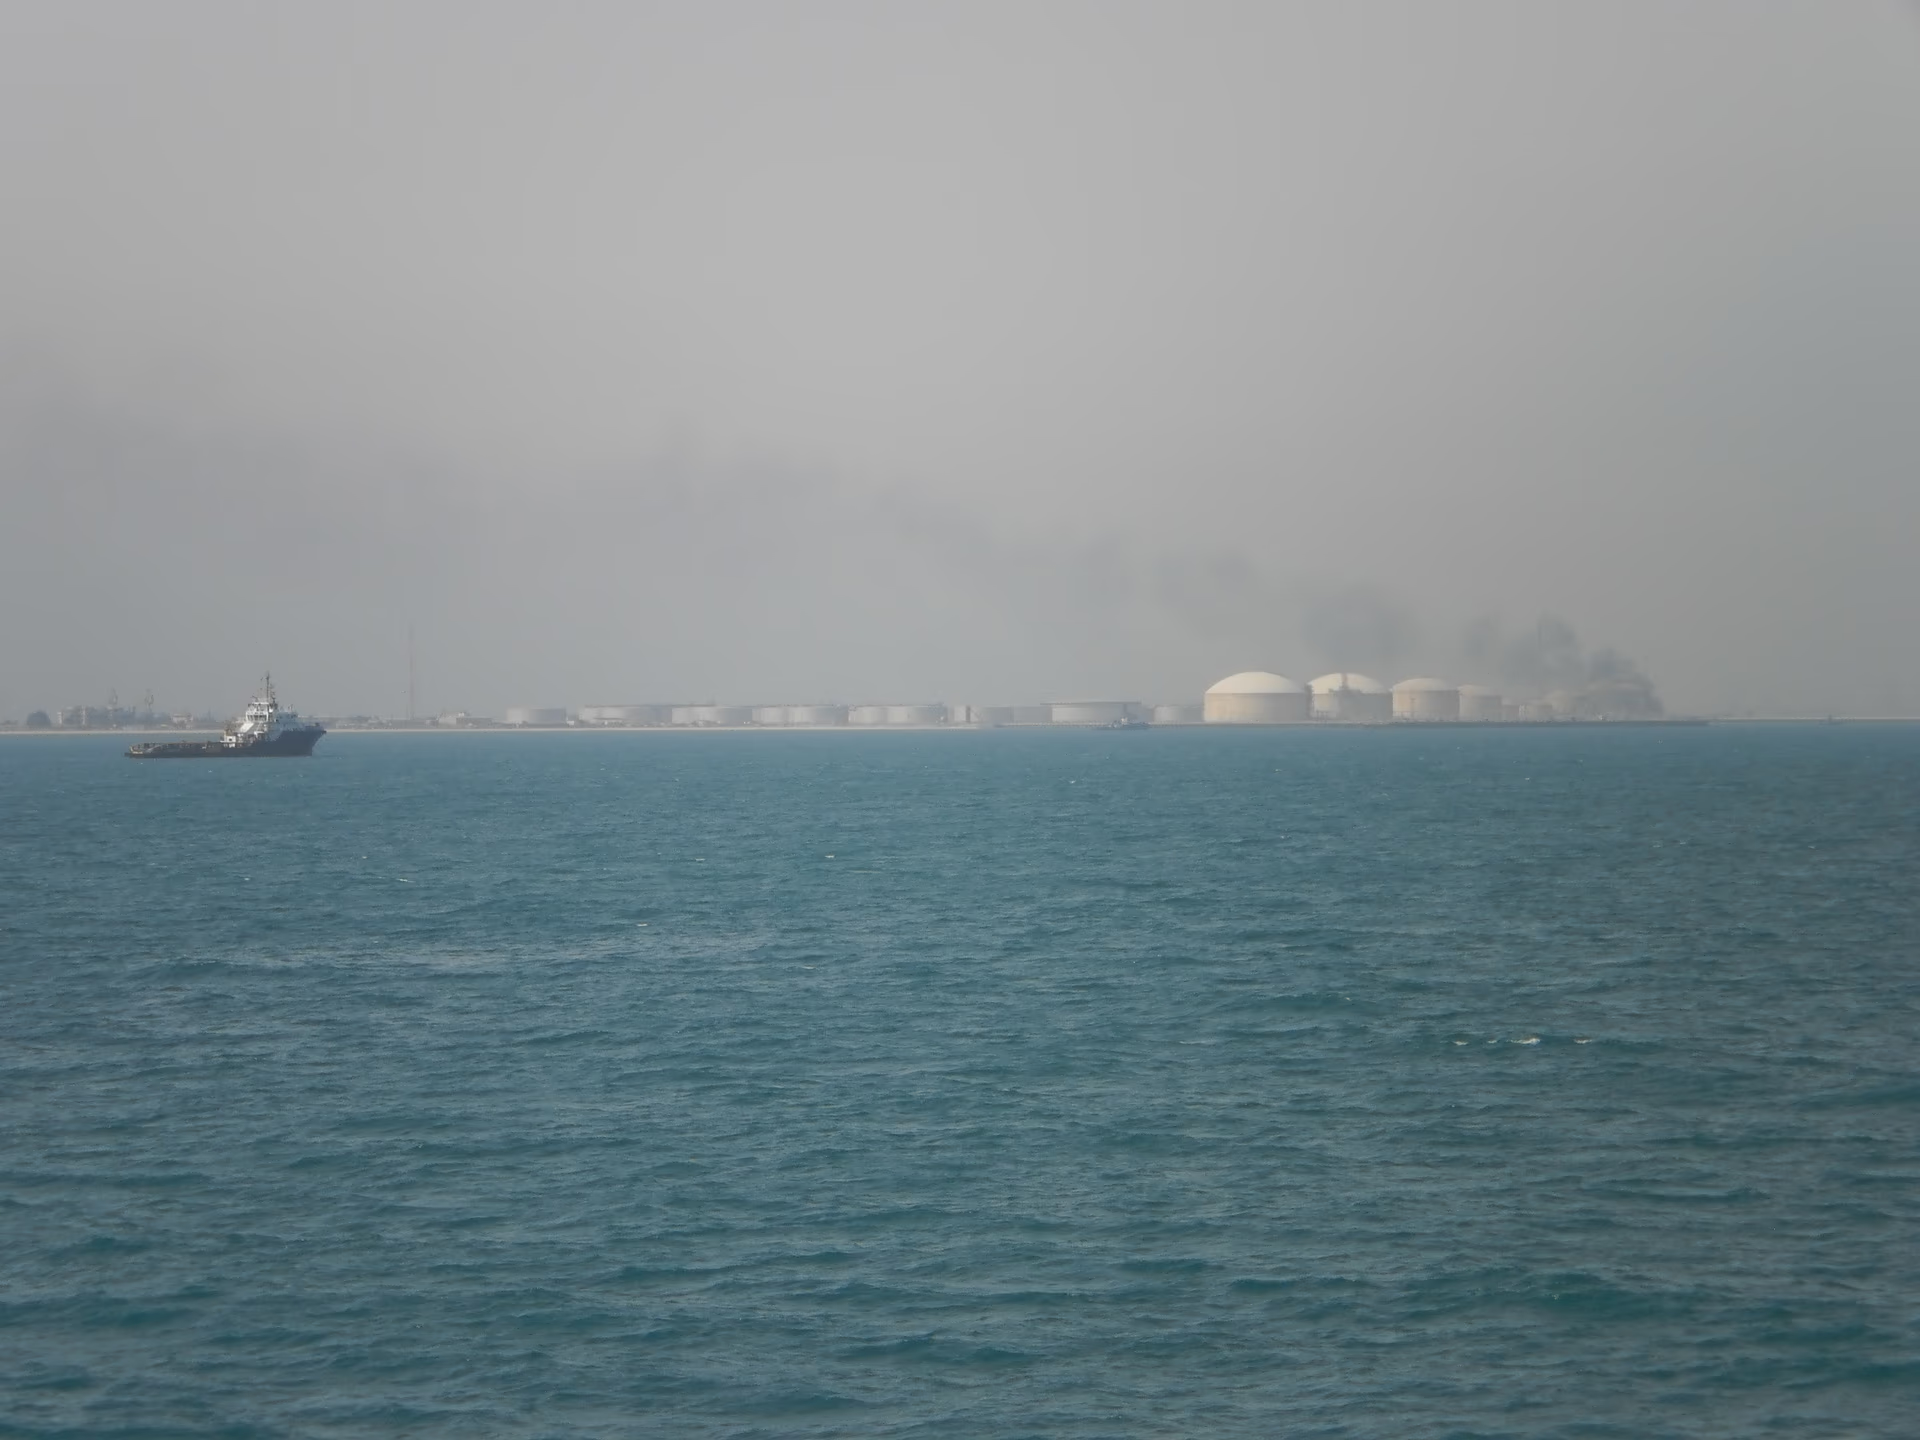
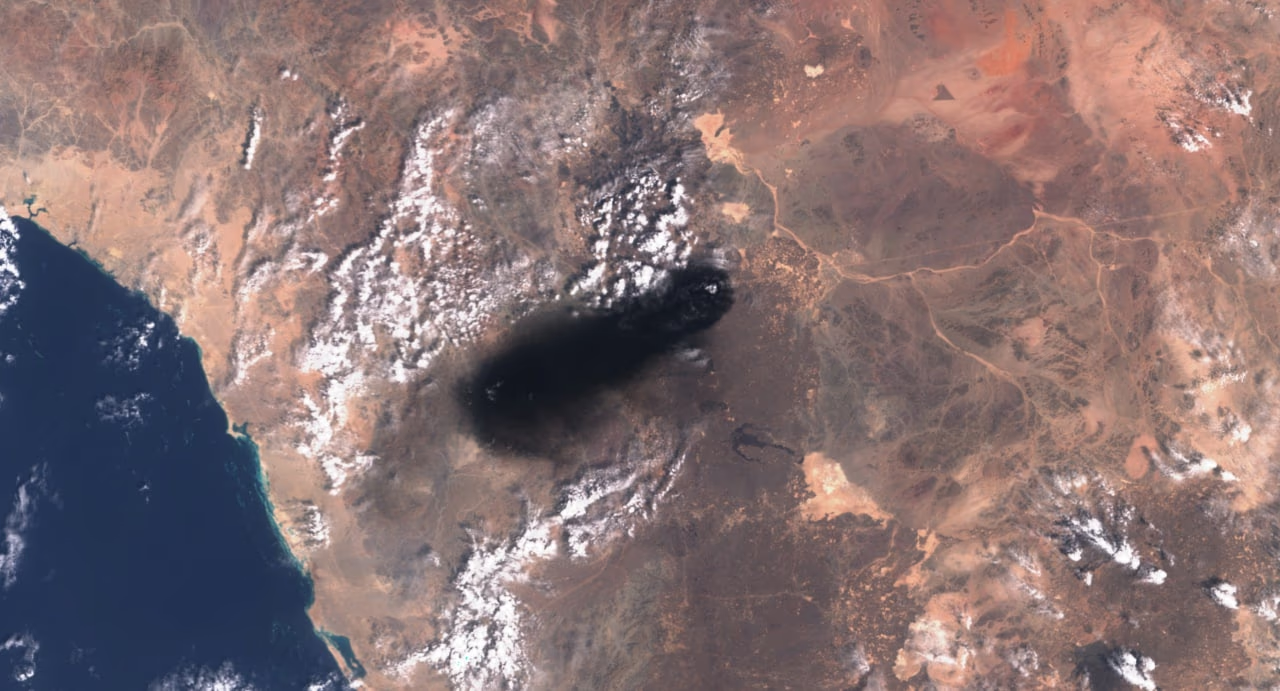
Saudi Arabia shut its East-West Crude Oil Pipeline on September 11 after a drone strike on a pumping station four days earlier caused a fire at the facility. The pipeline runs 1,201 kilometres from the Abqaiq oil field in Saudi Arabia's Eastern Province to the Red Sea port of Yanbu. At its post-2026-expansion capacity of 7 million barrels per day, the route serves as the country's primary Hormuz bypass, allowing crude exports to reach Asia via the Red Sea without passing through the Strait of Hormuz.
Saudi Aramco told markets on September 16 that it can restore roughly half the pipeline's capacity within days and return the full route to service in approximately six weeks. That guidance set the framework for Thursday's market positioning. The stock of alternative arrangements, including doubled tanker loadings at Ras Tanura and an activated loading route through Sohar, Oman, has partially offset the disruption, as detailed in Oil Authority's coverage of the bypass operations.
Expert Timelines Diverge Sharply
U.S. Energy Secretary Chris Wright told CNBC on September 15 that the pipeline outage "will be measured in days," aligning with Saudi Aramco's public guidance on partial restoration. Andy Lipow, president of Lipow Oil Associates, offered a different assessment. Reviewing publicly available photographs of the damaged pumping station, Lipow said repairs will "take months."
The disagreement matters for market direction. A "days" timeline removes the primary supply risk before the end of September. A "months" timeline keeps the disruption premium embedded in prices through Q4 2026 and potentially into early 2027.
The $19.82 Risk Premium Built Into Thursday's Settlement
Goldman Sachs raised its year-end Brent target to $85 per barrel earlier this week, upgrading alongside Bank of America and HSBC as the pipeline crisis unfolded, per Oil Authority's earlier analysis of the analyst upgrades. Bank of America and HSBC raised their own targets into the $85-to-$92 range. Thursday's $104.82 settlement sits $19.82 above Goldman's revised year-end target, the lower bound of the post-upgrade consensus.
When Brent hit $109.44 on September 12, the gap above Goldman's $85 target stood at $24.44 per barrel. Thursday's settlement narrows that premium by $4.62 from the peak. At the current pace of retreat, the market is discounting the Lipow "months" scenario but has not yet moved to price in the Wright "days" scenario. If the partial restoration materialises before October, the spread between settlement and analyst targets should compress further.
How the East-West Pipeline Became Saudi Arabia's Critical Backup
Saudi Arabia built the East-West pipeline during the Iran-Iraq War in the 1980s specifically to allow exports without transit through the Strait of Hormuz. The route lay largely dormant for years as Hormuz remained passable. Saudi Aramco brought the pipeline to its full 7-million-barrel-per-day capacity on March 11, 2026, when Hormuz access became constrained by the current regional conflict. The original Oil Authority report on the pipeline shutdown, published when Brent was still rising toward its peak, is available here.
Canadian Oil Sands Producers Capture the Windfall
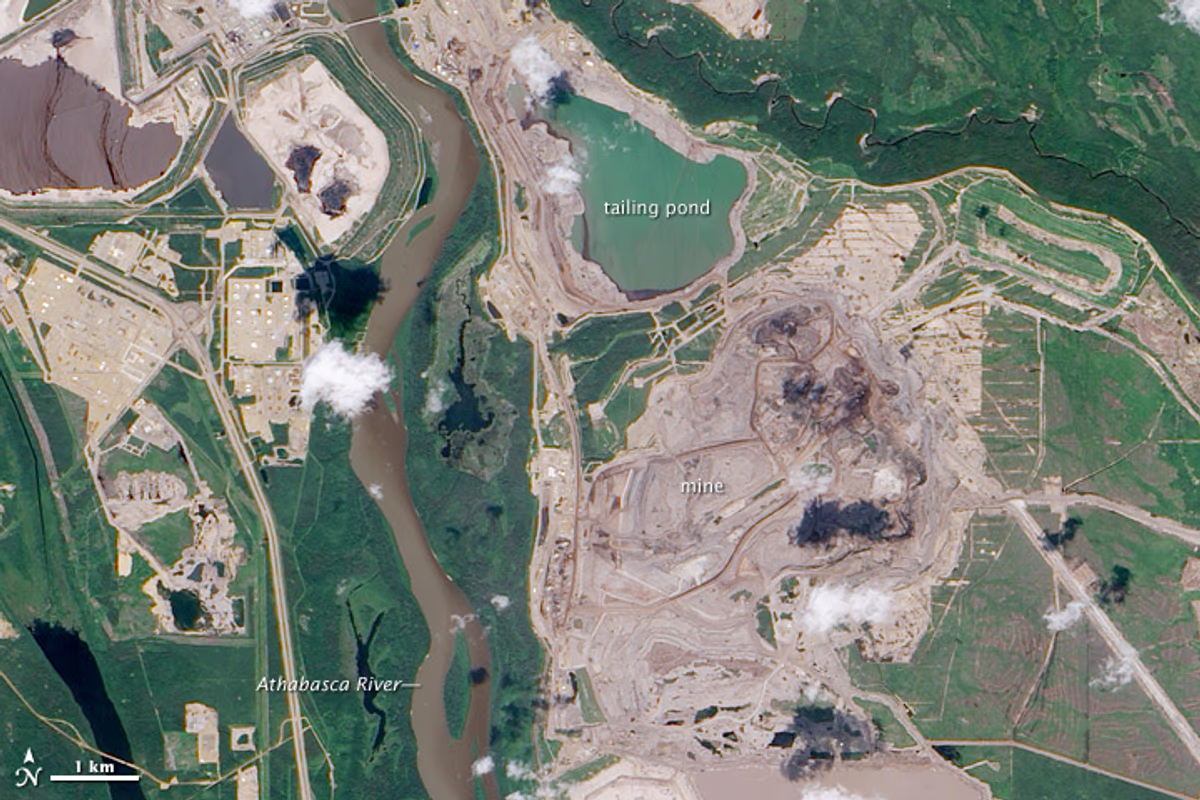
For Suncor Energy, which owns 58.74% of the Syncrude joint venture in Fort McMurray and operates the Petro-Canada retail and refining network, the current WTI level above $101 per barrel represents a clear margin lift. Western Canadian Select typically trades at a discount to WTI. With Trans Mountain Pipeline running near 95% of capacity since the 2024 expansion, the WCS-WTI differential has tightened relative to the pre-expansion era when Enbridge's Mainline was the primary export route.
At WTI's $101.91 Thursday settlement and a WCS-WTI differential of $12 to $14 per barrel, Alberta producers are realizing roughly $87 to $90 per barrel USD. Converting at current USD/CAD exchange rates near 1.38, that equals approximately $120 to $124 per barrel in Canadian dollars. Imperial Oil, ExxonMobil's Canadian subsidiary operating the Cold Lake thermal and Kearl oil sands projects, books in both USD and CAD and benefits from the currency translation. Canadian Natural Resources and Cenovus Energy, the latter including the legacy Husky operations it absorbed, also benefit at this WCS pricing level.
Outlook Through Q4 2026
Goldman's $85 year-end target implies analysts expect partial pipeline restoration and OPEC supply management to pull Brent back toward the $85-to-$92 consensus range before December. The six-week Aramco repair timeline, if accurate, brings full restoration by late October. That timeline would align with the Q4 rebalancing Goldman and peers are projecting.
Lipow's assessment introduces the alternative scenario: a months-long disruption keeps roughly 3.5 million barrels per day of Hormuz bypass capacity off the table through much of Q4. In that case, year-end Brent targets face upward revision, and Canadian producers continue to convert elevated WTI and WCS prices into higher CAD revenues. The next data point the market is watching is whether Aramco delivers on its own "within days" partial restoration commitment before the end of the trading week.
Published by Oil Authority, edited by Adam Humphreys
Submit a Correction
Spotted a factual error? Free account required to submit a correction.